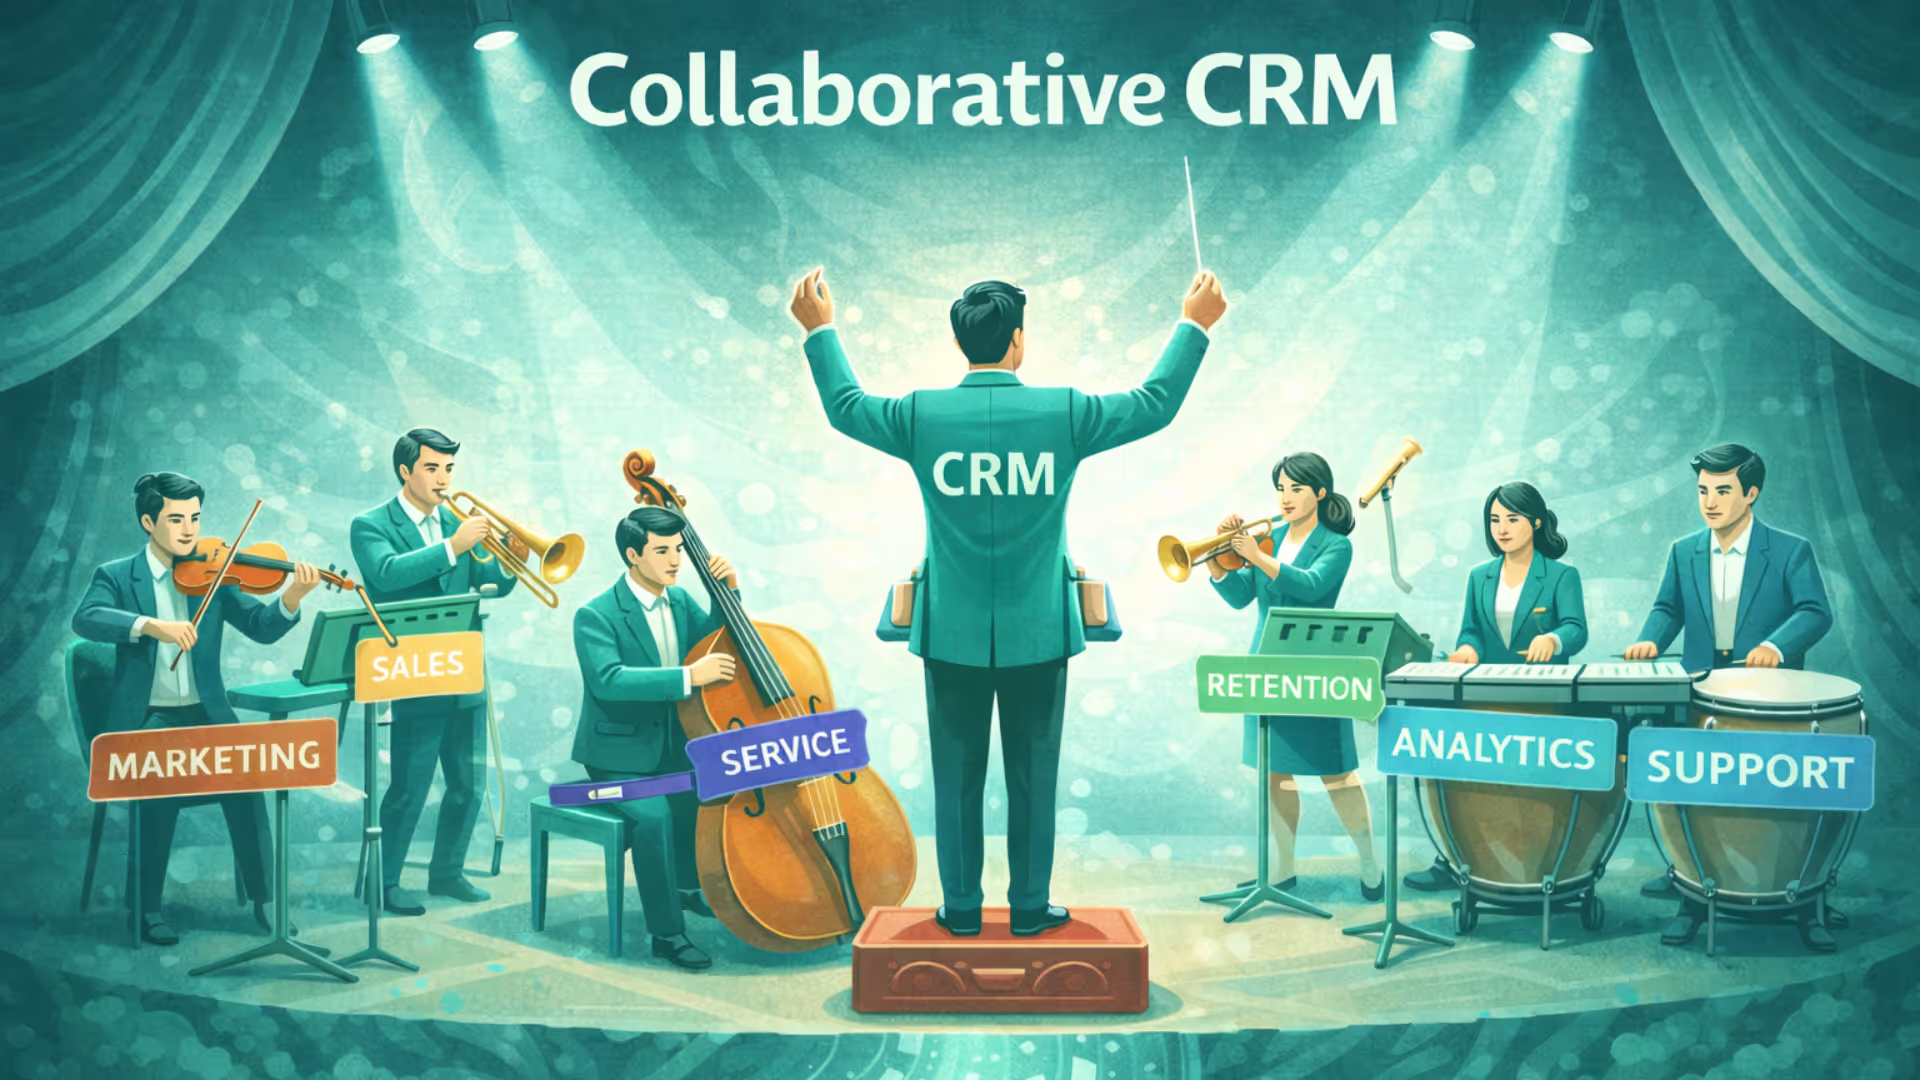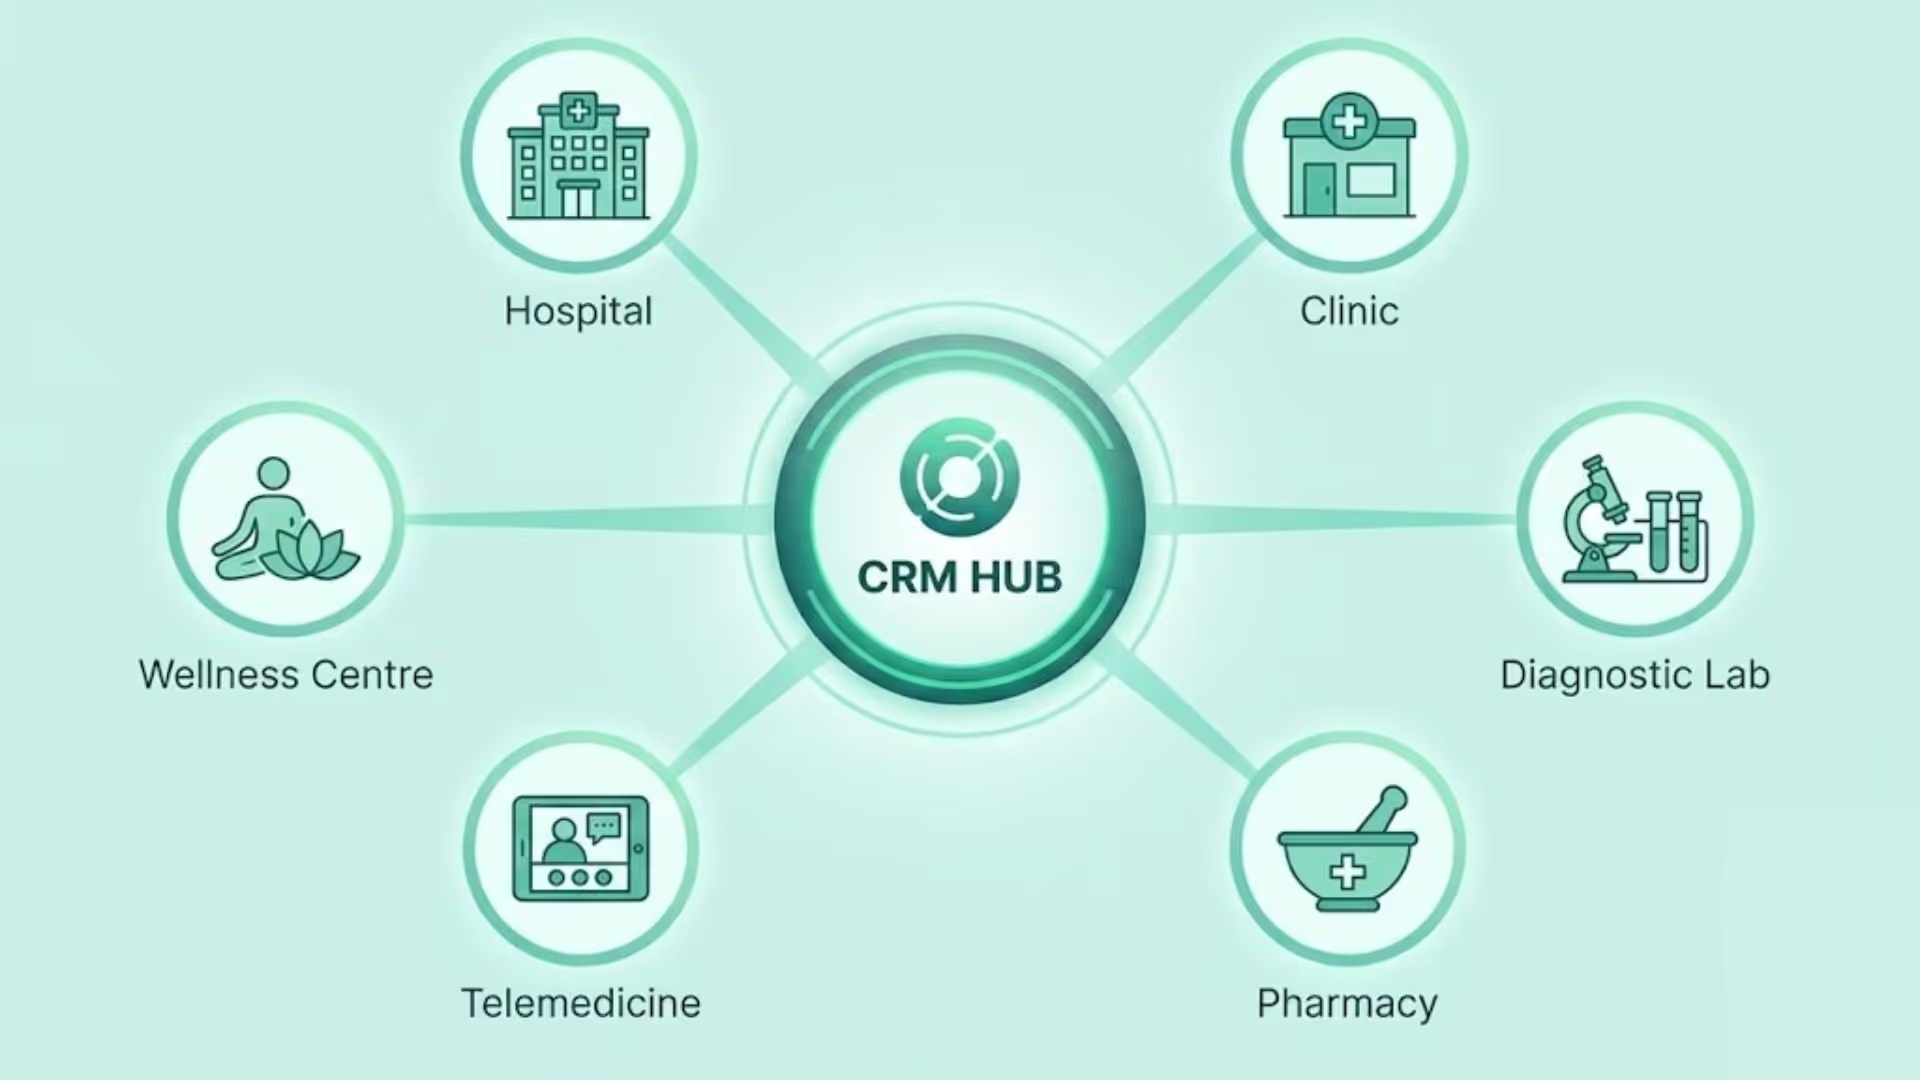


Relationships in the banking sector are built on trust. With an influx of leads and customers, data quickly piles up. A CRM solves this by centralizing your data, automating workflows, and enabling tailored services. For banks, the goal is to make customer relationships easier to understand and manage across branches, relationship managers, sales teams, service teams, and digital channels.
According to Alliedmarketresearch, the CRM market size of the banking industry was valued at $9.5 billion in 2021 and is expected to touch $39.2 billion by 2031, growing at a CAGR of 15.7%. Much of this expansion is owed to digital transformation, and shifting to a CRM from traditional methods is part of it.
While 48% of the bankers currently use a CRM, this guide will teach you how it transforms the banking experience, for both customers and bankers. You will learn about the features and benefits a CRM provides, how integrated AI aids with decision making and our best picks (best crm for financial advisors) to transform your processes.
What is a CRM for banks?
Besides the basic functionalities, CRM for banks offer:
- Secure handling of financial and personal data
- KYC, AML, and regulatory compliance tools
- Integration with core banking systems
- Relationship tracking across multiple accounts and products
- Multi-tier approval workflows
The CRM may support compliance-related workflows, but it should not be confused with the bank's regulatory framework or compliance function. In India, for example, RBI's KYC framework places customer-identification and customer-due-diligence obligations on regulated entities. A CRM can support the workflows around those obligations through capabilities such as document tracking, approvals, controlled access, and audit records, depending on the implementation.
The scope also varies by bank. A retail bank may prioritize high-volume customer acquisition and service, while a corporate bank may need stronger relationship mapping and account-level opportunity management.
What is a banking CRM software used for?
Banking CRM is not limited to sales. Its usefulness comes from the different relationship workflows it can connect.
Customer acquisition
Capture and manage enquiries related to products such as accounts, cards, deposits, loans, or other banking services.
Customer onboarding
Coordinate front-office onboarding activities, document requests, ownership, approvals, communication, and pending actions.
Relationship management
Give relationship managers a shared view of relevant customer interactions, open tasks, opportunities, and relationship history.
Customer service
Track service interactions, complaints, requests, ownership, and follow-ups across channels.
Cross-sell and relationship growth
Identify relevant opportunities to introduce additional products or services based on the customer relationship and the data available to the bank.
Referral management
Track referrals from branches, relationship managers, partners, campaigns, or existing customers and monitor their progress.
Corporate banking
Manage company-level relationships alongside contacts, decision-makers, opportunities, products, and interactions.
The specific workflows will differ across retail, commercial, and corporate banking. The CRM should therefore be evaluated against the bank's actual operating model rather than a generic list of features.
What is Retail Banking CRM?
Retail banking involves high volumes of customer relationships across products, channels, branches, and service interactions. A CRM can help teams manage these relationships beyond individual transactions.
Common workflows may include:
- Account or card enquiries
- Product leads
- Customer onboarding
- Branch follow-ups
- Service requests
- Renewals
- Campaign engagement
- Cross-sell opportunities
For example, a customer who recently opened an account may later enquire about a credit card. A connected CRM can preserve the interaction history and provide the relevant team with context before the next conversation.
What is a Corporate Banking CRM?
Corporate and commercial banking relationships are more complex than a single customer record. A bank may manage one company alongside multiple decision-makers, products, facilities, service requests, subsidiaries, and recurring interactions.
A corporate banking CRM can help teams connect:
Company → Contacts → Relationship Manager → Banking Products → Opportunities → Service Activity
For example, a relationship manager might manage a business relationship involving a CFO, finance team, multiple banking products, and several open requests. Relationship mapping allows the team to understand those connections instead of treating each contact as an isolated record.
What are the features & benefits of a CRM for banks?
Unified customer data
A customer’s financial profile consolidated in one place.
Lead and referral management
Tracks leads and referrals from all sources to drive sales conversion, while identifying key upsell and cross-sell opportunities.
Relationship mapping (individual → household → corporate)
Allows bankers to map/view relationships. For eg, if an individual account holder is linked to their family or a business they run.
KYC document management and verification workflows
Automates the capture, storage, and verification and periodic re-verification of KYC (Know Your Customer) documents such as ID proofs, PAN, Aadhaar, and address verification.
Integration with CBS (Core Banking Systems)
Automatically syncs customer’s financial profile (balance, transactions) and relationship data.
In practice, the exact data that should move between a CRM and the core banking system depends on the architecture, access controls, integration design, and which system is authoritative for each data element. The CRM should not automatically be treated as the source of truth for transaction or account data.
Loan origination and approval tracking
Tracks loan process from first touch point to last, i.e., from application, credit assessment, documentation, underwriting, to approval and disbursal within the CRM. For banks where lending is a major workflow, this may be connected to a dedicated loan-origination or lending system rather than being managed entirely inside the CRM.
Automated reminders and compliance alerts
Crucial for follow-ups, compliance checks, payment reminders, etc. Managers can configure alerts for portfolio reviews, credit limit renewals, or overdue accounts.
Role-based access and audit trails
Accessibility of sensitive information, for eg., loan details or lending history, is designed based on the user role - branch manager, RM, back-office staff. All user actions are logged in an audit trail.
Multi-channel communication
Logs all bank-customer interaction via email, SMS, WhatsApp, or secure in-app chat.
With Superleap, your inbox will be connected across channels, helping you manage customer communications effortlessly.
Security & compliance
Includes strong encryption, role-based access, and logging to meet banking regulations.
Embedded AI
Predicts churn, recommends next best action, performs sentiment analysis, and attends to customers 24/7 via chatbots.
AI can make a banking CRM more useful when it reduces manual analysis or helps employees surface relevant information faster. Depending on the implementation, useful applications can include:
- Conversation summaries
- Customer or lead prioritization
- Next-action suggestions
- Customer segmentation
- Cross-sell opportunity identification
- Service-assistance workflows
- Trend and churn-risk analysis
- Reporting and insight generation
Some of the examples above - particularly fraud detection, credit decisions, risk scoring, or other regulated financial decisions may require specialized systems and controls outside the CRM. They should not be treated as interchangeable with ordinary CRM automation.
AI should therefore be presented as an assistive layer rather than a replacement for banking judgment, governance, or regulated decision-making.
What is CRM for Branch Banking?
Branch teams may receive walk-in enquiries, referrals, product requests, service issues, and other customer interactions that need ownership and follow-up.
A banking CRM can help standardize how those enquiries are captured, assigned, updated, and reported across branches. For multi-branch banks, the same framework can provide location-level visibility while preserving centralized relationship data where the architecture supports it.
How to choose the right banking CRM software?
Ask yourself these questions before you decide on one CRM for the BFSI sector:
- Does it follow all necessary guidelines for data protection?
- Does it integrate with connecting tools? (for eg., core banking or policy systems)
- Does it allow omni-channel communication?
- Is it scalable? (ability to handle large volumes of data as business grows)
- Is it mobile accessible?
Before choosing banking CRM software, evaluate the system against actual banking workflows rather than only its feature list.
How to implement a banking CRM
Choosing the CRM is only the beginning. The implementation needs to establish what the CRM owns, what other systems own, and how information moves between them.
1. Map the current workflow
Document how branches, relationship managers, sales teams, service teams, and other stakeholders currently handle customer relationships.
2. Define system ownership
Decide which platform remains authoritative for customer, account, transaction, loan, or other specialized data.
3. Clean existing data
Identify duplicate records, outdated information, missing fields, and other data-quality issues before migration.
4. Define permissions
Decide who should be able to access, edit, approve, or export different types of customer information.
5. Configure workflows
Set up lead assignment, onboarding steps, reminders, service workflows, approval paths, and other recurring processes.
6. Integrate the relevant systems
Connect the CRM with the systems that need to exchange information while avoiding unnecessary duplication of authoritative data.
7. Pilot with end users
Test the CRM with relationship managers, branch staff, or other actual users before expanding it across the organization.
8. Measure adoption
Review whether employees are using the CRM consistently, whether required information is being captured, and whether the workflows are actually reducing manual work.
Best CRM for banks and financial institutions
Superleap CRM provides a 360 degree view of client profiles, with hyper-personalized engagement and an automated sales & service workflow. The system ensures compliance with banking regulations establishing robust risk management, best for mid-to enterprise level businesses.
Other options include CRMNEXT and Microsoft Dynamics 365 for finance.
Beyond just storing data, a CRM for banks is crucial to uphold the trust customers place in your institution, providing them secure experiences each time.
Book a demo with Superleap AI CRM today and make the investment. Thank us later.